A 398 credit score, private capital, and a foreclosure three months before Lehman collapsed. Your first deal's job is to make you someone who closes.
By J. MasseyJune 11, 2026· 8 min read
Share
Disclosure: This post may contain affiliate links. If you purchase through our links, we may earn a commission at no extra cost to you. We only recommend tools and services J. Massey's team actually uses. Read the affiliate disclosure
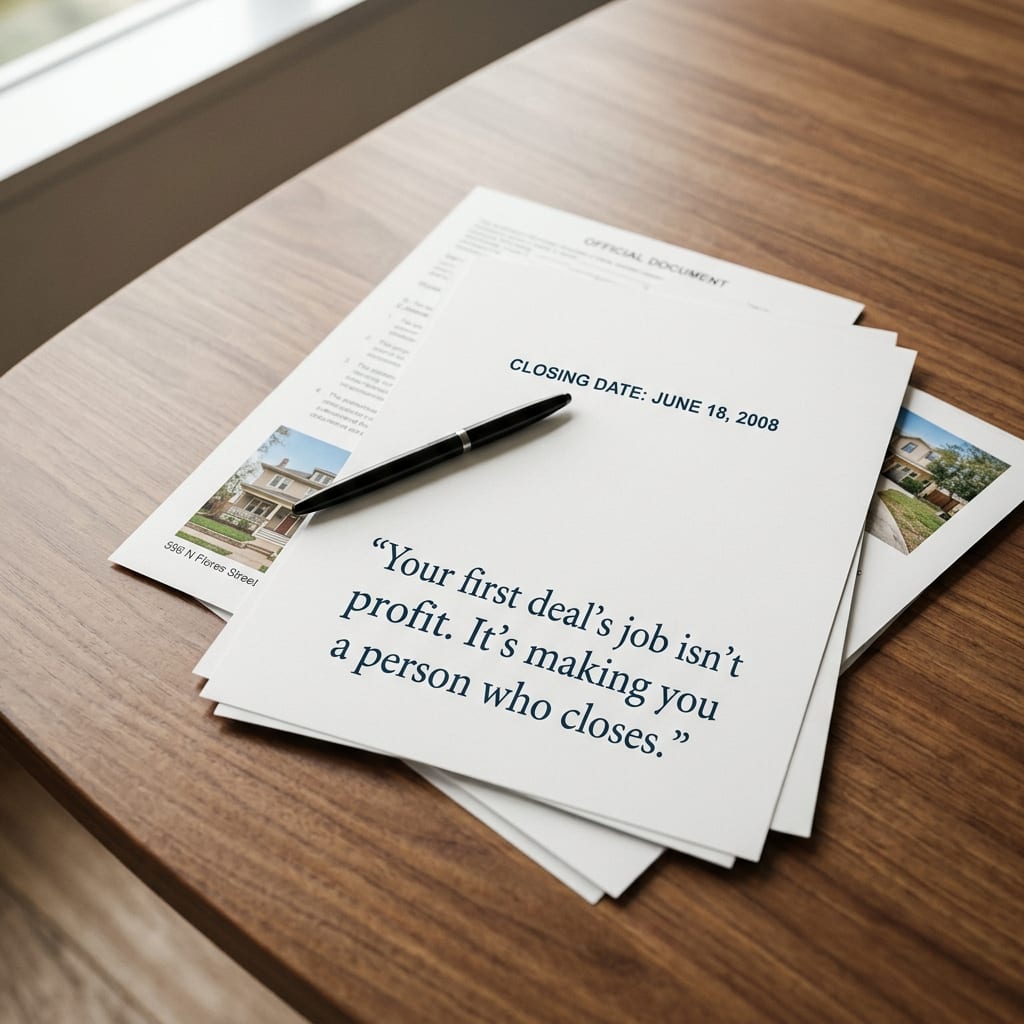
I closed my first property — 596 North Flores Street in San Bernardino, California — on June 18, 2008, with a 398 credit score, no cash of my own, and while I was living in a bank-owned house. Three months later Lehman Brothers filed for bankruptcy and the credit system seized. That deal is old enough to vote now, and the honest lesson from it is not that timing does not matter. It is that your first deal's job is not profit: its job is to turn you into a person who closes, because everything you build afterward runs on skills only a closed transaction can teach you.
This is what actually happened, what the market was doing around it, what the deal cost me, and how to size a first deal so that being wrong is survivable.
I've spent 18+ years in real estate, focused on short-term rentals since 2016, trained more than 10,000 operators through CashFlowDiary, and recorded 704 published CashFlow Diary™ podcast episodes breaking down the deals that work and the ones that don't. The pattern below shows up in every cycle.
Last updated: 2026-09-17
Interactive · run your own numbers
When does an arbitrage unit pay you back?
$2,200
$180
70%
$10,000
Monthly profit
$1,330
after lease + ~25% opex
Months to recoup setup
7.5
then it's pure cash flow
First profit lands in
Month 2
Compare that to 18+ months for new-build ownership.
I did not close into a friendly market. I closed into the end of the largest housing expansion in modern US history and the beginning of its unwinding.
The Federal Reserve's own history of the period records that average US home prices more than doubled between 1998 and 2006, the sharpest increase on record, that homeownership rose from 64 percent in 1994 to 69 percent in 2005, and that the US economy entered recession in December 2007 — six months before my closing (Federal Reserve History, The Great Recession and Its Aftermath). The same essay notes Bear Stearns was absorbed by JPMorgan Chase in spring 2008 with Federal Reserve assistance, and that Lehman Brothers filed for bankruptcy that September.
The credit machinery that produced my situation is documented too: subprime lending expanded through private-label mortgage-backed securities, New Century Financial filed for bankruptcy in April 2007, and when the bond funding collapsed, lenders stopped writing those loans (Federal Reserve History, Subprime Mortgage Crisis).
So conventional wisdom was right that this was a terrible time to buy on conventional terms. It was also the moment when foreclosed inventory was priced for people willing to solve problems. If you want to check what any market did before or after a moment like that, the primary series is public (FHFA House Price Index).
596 North Flores Street, San Bernardino — the 2008 first deal that started the sequence
Before the deal, my conditions were these: no college degree, not enough money to eat consistently, no clear idea where next month's money came from, and a lot of people telling me to go back to school or get a job. Those options did not fit, and I knew it before I could explain why.
What I knew I needed was a shut-up check. Not a fortune. Not a portfolio. A check big enough to quiet the noise in my head and buy enough credibility with the people around me that they would let me take care of my family my own way.
"Comfort kills dreams long before failure does."
— J. Massey · CashFlowDiary
That was the motivation. Not strategy. Survival, plus the need to prove I had agency at a moment when both agency and autonomy felt under threat.
The Blueprint I Already Had
Before real estate I sold on eBay. Not products I owned — products I bought at garage sales for a few dollars, repackaged, repriced, and listed where the addressable market was larger and the economics were different. The seller got what they wanted. The buyer got what they wanted. I contributed time, knowledge of what would sell, and the willingness to move goods between two markets that were not talking to each other.
That was the blueprint. I did not know it yet.
When a friend told me to look at real estate, the same logic applied. A house sitting in foreclosure was not reaching the buyer who needed it. I could be the person who moved it. The canvas changed; the logic did not.
I also had nothing better to offer. My own best ideas had produced the situation I was trying to escape, so I did what my mentor said, exactly as he said it. Sometimes not knowing enough to argue is an advantage.
What the Closing Table Actually Felt Like
Surreal is the only word I have. Almost out-of-body. And underneath it ran an irrational loop: somebody is going to find out I am living in bank-owned property and take this from me. Too good to be true. Not for someone from Fayetteville, North Carolina, 28306.
But it closed. A 398 credit score, private capital I had to go find because I had no cash, and terminology I was learning mid-transaction.
What I understand now is that it closed because I had no other option. Comfort kills more plans than failure does, and I did not have the luxury of comfort.
Study mode vs. operator mode — the identity shift happens at the closing table
596 North Flores was in rough shape. The numbers were not clean. I made mistakes, some paid for in time and some in money. It was not a masterclass in execution.
What it was: the transaction that made me someone who closes. That identity shift is the real asset. Before the closing I was someone trying. After it, I was someone who had done it — and those two people make different decisions about the next opportunity. By the second property I was not guessing, because I had run one address rather than studied one.
Here is how I would score a first deal, and it is not on cash flow.
Scorecard item
Weight
Why it matters more than profit
Did it close
40%
Closing is the skill; everything else is commentary
Was the downside capped in writing
25%
Contingencies, reserves, and exits keep a bad deal survivable
Did you build a repeatable file
15%
Checklists, contacts, and numbers become deal two's head start
Did you meet the operators
10%
Lender, agent, cleaner, inspector, manager — your future bench
Cash flow in year one
10%
Nice to have; the smallest teacher in the list
What Waiting Costs, in Numbers You Can Fill In
Beginners ask, "What if I buy the wrong deal and lose everything?" Operators learn to ask, "What does waiting cost me in compounding experience, equity, and income?"
Run this table with your own figures before you decide to wait another quarter. Every line is an estimate you control, and estimates you write down argue back.
Cost of a capped mistake
Cost of another year of waiting
Earnest money you agreed to risk
Twelve months of rent or mortgage on a place that pays you nothing
One or two months of carrying costs
A full seasonal cycle of pricing data you never collected
Inspection and legal fees
The lender, insurer, and manager relationships you did not start
A specific, written lesson
The same fear, one year older
The first column has a ceiling you set. The second has none, and nobody invoices you for it, which is exactly why it goes unpaid attention.
One address became a system. The system became a portfolio. The portfolio became a company that has trained more than 10,000 operators. All of it traces back to one foreclosed property in San Bernardino in 2008. If I had waited for a better entry point, I would have traded years of compounding for a slightly cleaner start.
That is a description of my path, not a promise about yours. Financing, insurance, licensing, and tax treatment vary by market and change over time. Verify current rules with your municipality, and review any purchase, lease, or partnership document with a licensed attorney, a CPA, and your insurance carrier before you sign (IRS Topic No. 415, Renting Residential and Vacation Property is a starting point on the tax side, not a substitute for advice).
One address becomes a system, the system becomes a portfolio
He deserves to hear: you have this. He deserves people around him who believe him. He deserves to know the thing he is most afraid of will not happen, and that what does happen is something he cannot picture yet.
He deserves to know the systems he is building to survive will be copied by people he has not met, who will thank him for a life he had no idea he was helping build — while he was mostly trying to eat.
If you are wondering whether people like you get to do this: yes. Not because conditions are perfect, and not because you have it figured out, but because the operators who build real portfolios are the ones who moved, learned what the waiting crowd never learned, and built systems out of early mistakes.
If you want help sizing your own first deal so the downside is capped in writing, book a complimentary one-on-one diagnostic call and bring the address you are looking at.
Frequently Asked Questions
Do I need good credit to close a first real estate deal?
Not necessarily. I closed mine with a 398 credit score using private capital, which is priced on the deal and the operator rather than your FICO score. Conventional financing does depend on credit, so the honest answer is that poor credit narrows your options and raises your cost of capital — it does not automatically end the conversation.
What if I don't have cash to close?
Then your first job is capital, not property. Private lenders, seller financing, and partnerships all trade capital for structure and returns. Get the terms in writing, model the deal at the real cost of that money, and have a licensed attorney review the documents.
Should I wait for a better market before buying?
Waiting is a position with a price. I bought into the worst headlines in modern housing history and the deal still taught me the skills the next twenty transactions ran on. Judge the specific deal — its terms, its downside, your reserves — rather than the national narrative.
What's the biggest mistake first-time investors make?
Permanent preparation, followed closely by an uncapped downside. The fix is the same in both cases: define in writing what you can lose, then act inside that boundary this month.
What if my first deal goes wrong?
If you capped it, you pay in months and lessons rather than years and solvency. Write down the exit before you sign: contingencies, reserves, who buys or leases it if your plan fails, and the number at which you walk away.
Where does rental arbitrage fit for a beginner?
It is the same move I made on eBay — control an asset between two markets without owning it. You learn operations, guest management, and pricing before you take ownership risk. It requires a landlord's written permission and local rules that allow it, so verify both before signing anything.